You can have a retirement plan that says you’ll never run out of money and still be missing some important opportunities. That’s what I found when I reviewed a plan for Tim and Laurie, a couple in their early 60s with just under $2.1 million in net worth.
Their original plan suggested they could retire comfortably. But after looking at their taxes, withdrawal strategy and, most importantly, what they wanted retirement to look like, we ended up with a very different plan.
The starting point: $2.1 million in net worth
Tim and Laurie had roughly $1.7 million in investable assets. The original plan allowed for about $45,000 in ongoing annual spending, plus separate amounts for travel and home renovations in the early years. It showed their money lasting through retirement.
On paper, that looked fine. But when I asked how they had arrived at the decisions in the plan, they couldn’t tell me much about the trade-offs. Nobody had really walked them through when to start CPP, which accounts to withdraw from or what would happen to their taxes later in retirement.
The plan answered one question: Can we afford to retire? I wanted to answer another: Are we making the most of the money we’ve saved?
The first problem: unused low-income years
Tim was 63 and planned to retire on his 64th birthday. His original plan had him convert his RRSP to a RRIF at retirement, start CPP at 64 and start OAS at 65. Laurie had already been retired for four years. Her plan was to wait until 71 to convert her RRSP and start CPP and OAS at 65.
In the 2026 cash-flow projection, Tim had $90,000 in employment income and just over $6,000 in CPP. Laurie had essentially no personal taxable income. They were also drawing from non-registered savings and making TFSA contributions.
That imbalance caught my attention. Canada has a progressive income tax system. If one spouse has very little taxable income, there may be an opportunity to withdraw some RRSP money at lower rates rather than leave it all to be taxed later.
For a Manitoba resident in 2026, taxable income around $70,000 falls in a combined federal and provincial marginal bracket of approximately 33.25%. That is the rate on the next dollar of ordinary taxable income, not the rate on every dollar earned. See the CRA’s current tax brackets.
Laurie had already spent several years in a low-income position. Those years cannot be recovered. I wanted to know why the plan wasn’t using them more deliberately.
The second problem: taking only the RRIF minimum
The original strategy was largely to convert the RRSPs to RRIFs and then take only the required minimum withdrawals. A RRIF generally requires a minimum withdrawal beginning in the year after it is established, but that minimum is a rule, not a recommendation about the best amount to take.
The projections showed the registered accounts continuing to grow. By the end of the plan, Tim and Laurie were projected to have more in their RRIFs than when retirement began.
That might look like success until you remember that RRIF money is tax-deferred, not tax-free. The timing of withdrawals matters, especially when one spouse dies.
What happens when one spouse dies?
The original projection assumed Tim died at 90 and his RRIF transferred to Laurie under the spousal rollover rules. That transfer can defer immediate tax, but Laurie would then be responsible for withdrawals from a much larger registered balance. Her taxable income could rise, potentially triggering Old Age Security recovery tax.
When Laurie later died, the projection still showed roughly $1.3 million in her RRIF. With no qualifying rollover in this example, the remaining RRIF value would generally be included in income on the final tax return. The CRA explains the tax treatment of RRSPs and RRIFs at death.
The projected estate was smaller than it first appeared
The original report showed Laurie ending retirement with approximately $5.6 million in net worth. But that headline figure did not reflect the tax that would be payable on the remaining registered money at death.
Once I accounted for that projected tax, the estimated after-tax estate fell to approximately $4.69 million. That was nearly $1 million less than the figure they were looking at.
I wanted to see whether changing the withdrawal strategy could improve the result.
What changed in the revised retirement plan?
1. Use the lower tax brackets
Rather than automatically taking only RRIF minimums, I tested withdrawals designed to bring each spouse’s taxable income to approximately $70,000 a year. We first counted taxable investment income and government benefits, then used additional registered withdrawals to reach the target.
That target was specific to this case and the planning assumptions. It isn’t a universal rule for Canadian retirees. The right withdrawal amount depends on tax brackets, investment income, benefits, future income, spending and estate priorities.
2. Revisit CPP and OAS timing
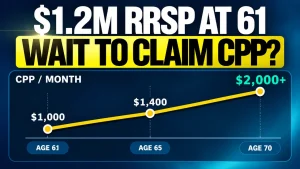
I also tested delaying both CPP and OAS to age 70. Doing so created a longer window to draw down registered savings before government pensions added more taxable income.
Delaying CPP after 65 increases the monthly pension by 0.7% for each month, up to 42% at 70. Delaying OAS after 65 increases it by 0.6% per month, up to 36% at 70. Those increases are real, but delaying is not automatically the best choice for everyone. Health, cash-flow needs and life expectancy matter. See Service Canada’s CPP guidance and OAS guidance.
3. Check the actual TFSA contribution room
The original plan assumed ongoing TFSA contributions, but the couple had not reviewed their available room. When we checked, both Tim and Laurie had approximately $32,000 of unused contribution room.
The revised plan used that available room and directed excess registered withdrawals not needed for spending toward TFSAs or non-registered accounts. TFSA room needs to be checked against personal records and CRA information before contributing, since CRA figures may not yet reflect recent transactions.
The tax-planning result: more than $1 million in projected estate value
With those changes, registered balances began falling earlier instead of growing unchecked. The plan reduced the risk of a large taxable RRIF being left to the surviving spouse and reduced the projected tax exposure at the second death.
Under the revised withdrawal and benefit assumptions, the projected after-tax estate increased from about $4.69 million to $5.84 million—an improvement of approximately $1.15 million. Those are results from Tim and Laurie’s planning projections, not a guaranteed saving or a result other households should expect.
For more on why the order and timing of withdrawals matter, see my article on the cost of delaying your retirement withdrawal strategy.
But building the largest estate wasn’t their goal
Here’s where the conversation changed. Tim and Laurie weren’t asking me to leave the most money possible to their estate. They wanted to travel, spend time with family and friends, and have the flexibility to say yes to things they enjoyed.
Their original spending number had been more of an estimate than a thoughtful decision. They had never retired together before. How could they know exactly what they would spend?
So we rebuilt the spending assumptions around what mattered to them. Ongoing spending increased from $45,000 to $72,000 a year. Their travel budget increased from $20,000 to $40,000 a year. The travel amount was a separate planning assumption, not necessarily included in the $72,000 ongoing-spending figure.
Even with that additional spending, the revised projections still supported their retirement under the model’s assumptions. That does not eliminate market, inflation or longevity risks. It means the plan was now being used to test the life they actually wanted, rather than simply to produce the largest ending balance.
A retirement plan should answer more than ‘Will I run out?’
There is value in knowing your savings are projected to last. But that is only the starting point. A good retirement plan also asks who should withdraw money, when those withdrawals should happen, how government pensions fit in and what you actually want the money to do.
For Tim and Laurie, tax planning created options. The more important result was that they could consider enjoying more of their savings while they were healthy enough to do so.
If your retirement plan has never gone much further than showing you a green light, it may be worth revisiting the assumptions behind it. Our Atlas System starts with what’s important to you, then builds the income, tax and investment decisions around that.
This article is for general educational purposes. The figures are case-specific projections and depend on the assumptions used; they are not guarantees or personalized financial or tax advice.